Sourcing is the first part of the acquisition funnel to get right. A strong sourcing engine gives you access to better businesses, reduces competition for deals and helps you build relationships with owners long before they are ready to sell. But sourcing at the smaller end of the market is rarely straightforward. Many attractive businesses are never formally put up for sale, financial information is often limited, and owners may take years to decide whether to sell.
This chapter covers how acquirers of UK and continental European businesses below €2m EBITDA find sellers, win their trust and manage a pipeline. The timelines and conversion rates quoted are practitioner rules of thumb that vary widely by sector and country, so treat them as approximate.
In Europe, a significant share of sellers at this size are founder-owners approaching retirement with no family successor. In Germany alone, ~300,000 retiring SMB owners lack any succession plan and face liquidation1. The same generational shift is playing out across Europe, with many of these businesses too small to attract traditional private equity. This creates a significant opportunity for micro buy-and-build platforms.
But retirement is only one reason owners sell. Understanding a seller's motivations is critical, as they shape everything from deal timelines and price expectations to the risks a buyer inherits.
Why owners sell, and what each reason means for the deal:
| Trigger | Typical seller behaviour | Watch out for |
|---|---|---|
| Retirement, no successor | Patient; cares about legacy; open to a 1–2 year handover | Owner may have stopped investing in the business years ago |
| Burnout or fatigue | Motivated, wants a fast exit | Recent under-investment; weak second layer of management |
| Death or ill health | Estate or family sells, often with urgency | Little or no owner handover; knowledge leaves with the owner |
| Partner disagreement or divorce | Price tension between shareholders | Partners with different ages and goals can block or delay |
| Distress | Needs to sell, sometimes framed as retirement | Declining revenue or lost clients hidden behind the story |
| Rising regulatory or IT burden | Can't afford the investment the business now needs | Compliance gaps you inherit |
Seller types also matter:
- Sole founder-operator: One decision-maker, but the business often depends heavily on them.
- Multi-partner firms: Common in accountancy and insurance brokerage (though less common in <€2m EBITDA businesses). Every partner must agree, and partners of different ages want different things.
- Second-generation family businesses: Family shareholders outside the business may have a say, and family politics can stall deals.
- A business with a strong second-in-command: That person may want to buy it themselves, making them a rival bidder. Or they may be your future managing director, which could be an interesting opportunity.
Field lesson: find out early who actually owns the shares, who will make the final call, and how the owner expects the sale to run: their timeline, whether they plan to bring in an adviser, and whether they're talking to other buyers. Ask about the process rather than about authority. "Who else would you want involved in this decision?" feels more natural than "Who decides?" Then check the shareholder register yourself, because the answer you get in a first meeting isn't always the full picture.
How you source a deal can have a significant impact on what you pay for it. At this size, competition between buyers is often a major driver of price. A business marketed through a broker may attract several bidders, while one approached directly may have only you at the table.
Good acquirers run several sourcing channels in parallel, each with different trade-offs. Brokers provide access to sellers who are ready to transact, with more structured and often faster processes. Direct outreach and referrals can offer less competition, more attractive entry prices and greater control over the process, but typically require more time and effort to convert into deals.
2.1 Brokers and sell-side boutiques
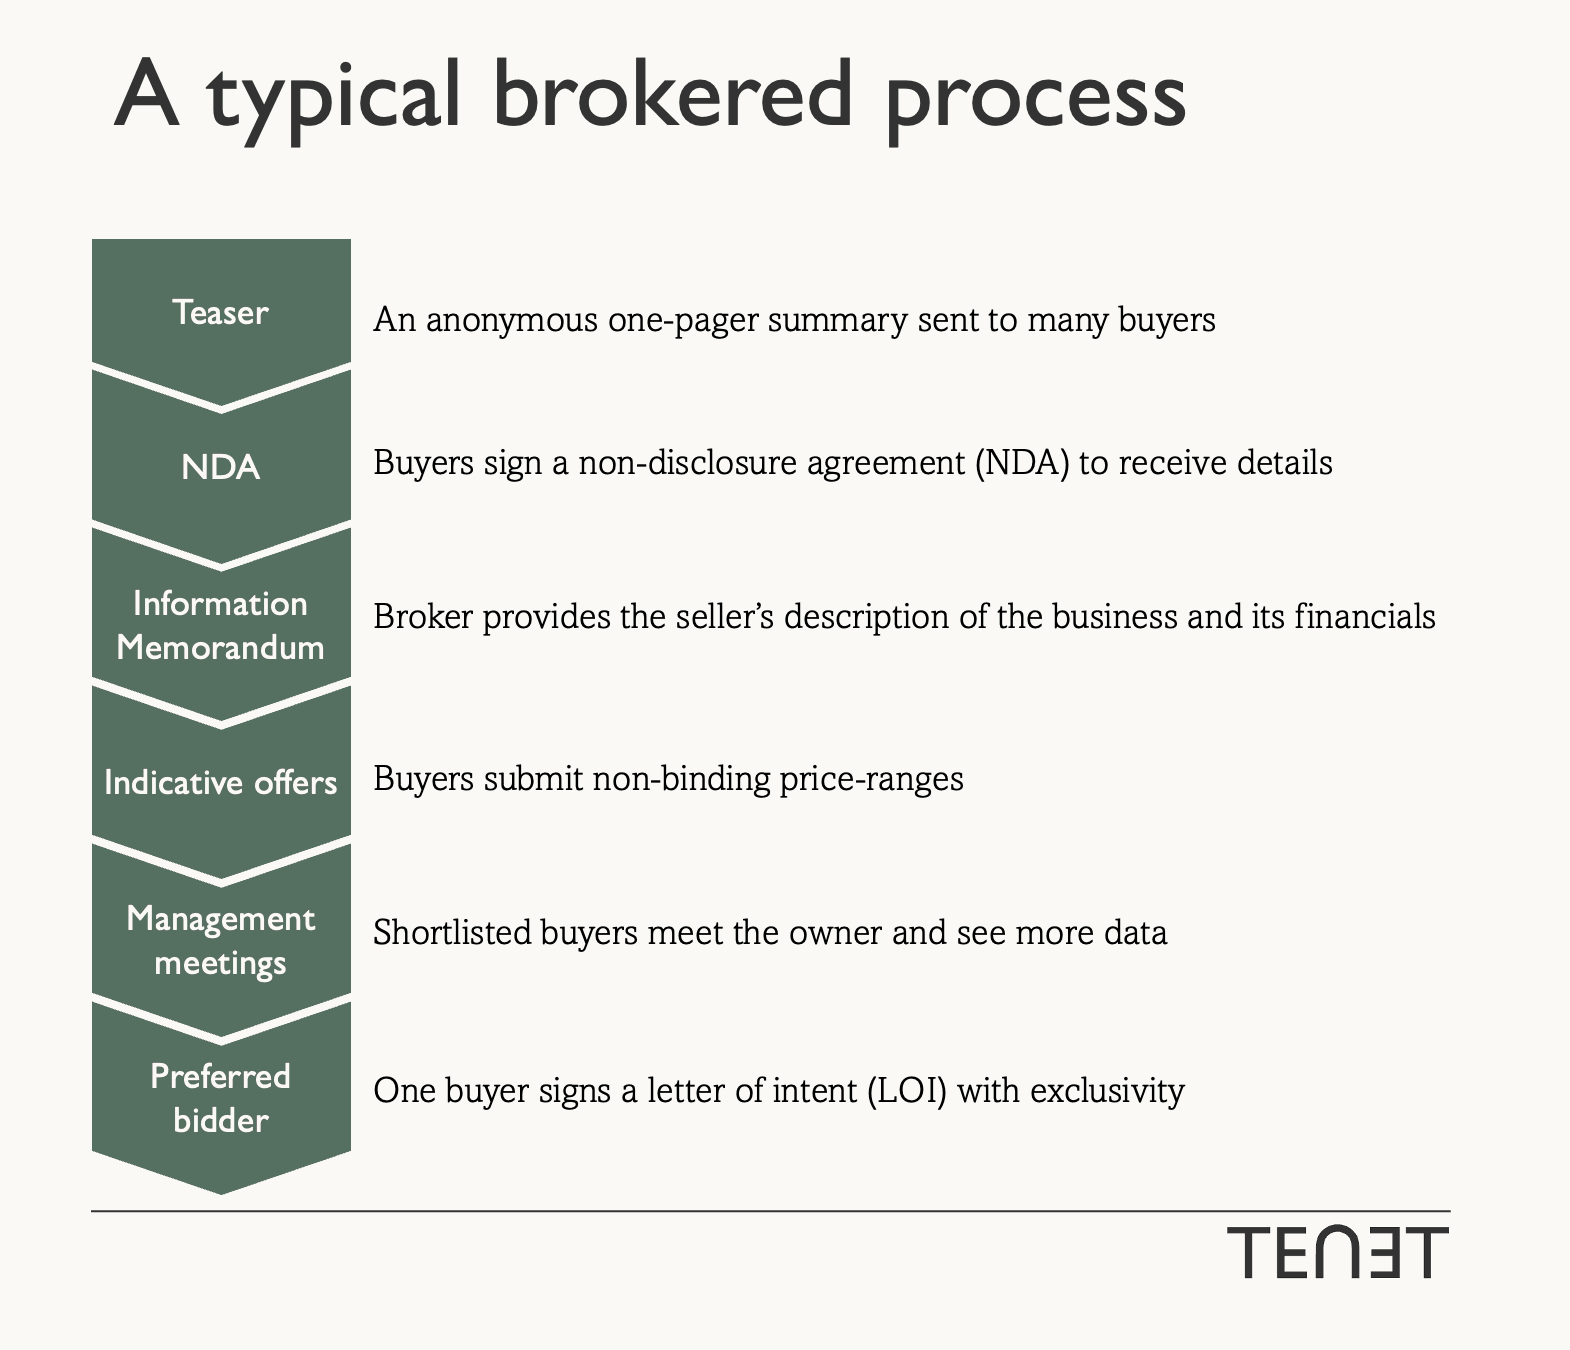
At this size, sell-side advisers are local business brokers, small M&A boutiques, and the corporate finance teams of regional accounting firms. Quality varies widely.
 (opens the image full size in a new tab)
How brokers are paid:
- Mostly a success fee from the seller, typically a few percent of deal value, often with a minimum.
- Some brokers charge substantial upfront fees rather than relying primarily on success fees. Understand their incentives, as these arrangements may provide less motivation to complete a transaction.
What this means for you:
- Upside: the seller has decided to sell, the information is packaged, and it moves faster.
- Downside: you face competition, and the broker is paid on price and completion, not on fit. The IM presents the business in its best light, with “adjusted EBITDA” as the most favourable version of the numbers, so much of what matters won’t be in it. You need to know which questions to ask to find it.
Field lesson: Good brokers remember which buyers close reliably and don't cut the price late. They call those buyers first next time. Being a known, reliable buyer is itself a sourcing channel.
2.2 Direct (proprietary) outreach
You build a target list from company registries and commercial databases, then contact owners by letter, email, phone, LinkedIn, or in-person.
- Registries differ by country. UK Companies House is free and searchable, but smaller companies disclose limited financial information. German filings are similarly limited, while Nordic registries, particularly in Sweden and Norway, offer much greater transparency. Buyers often need to combine registry data with headcount, sector and other commercial information to identify suitable targets.
- Regulated sectors come with ready-made target lists. Public registers list every authorised firm, such as the FCA register for UK insurance brokers, and professional bodies publish directories of their members, such as accountants and tax advisers. Combine them with company registry data to filter by size.
- Conversion is low and slow. Most owners say "not now". The value comes from systematic follow-up over months or years, so CRM discipline is the real capability.
- Message quality matters. Outreach that is local-language, specific to the owner's business and focused on their concerns converts far better than generic "we buy businesses" emails.
- "Proprietary" does not always stay proprietary. Once serious, some owners could hire an adviser or test your price with competitors. The real advantage is being first and trusted, not exclusive.
2.3 Intermediaries and referral networks
- The owner's accountant is often the first to know an owner is thinking of selling. They strongly influence who gets introduced and what price the owner expects.
- Lawyers, private bankers, wealth managers and chamber-of-commerce succession advisers also refer deals.
- These relationships rarely produce deals immediately. Regular conversations, sharing sector insights and demonstrating that you can complete transactions help turn professional advisers into recurring referral sources.
- Referral or finder's fees are common. Check they are disclosed to the seller and don't create conflicts, for example an accountant who also advises the seller on price.
2.4 Sector networks and previous sellers
- In a roll-up, acquired owners can become one of your most valuable referral sources. They know peers approaching retirement. A seller who had a good experience becomes a reference; a bad one poisons the well.
- Trade associations and sector conferences are useful. This is where owners and their trusted advisers gather, and some associations run succession programmes of their own. Go as a contributor, not a hunter. Speaking on topics owners care about, such as succession, regulation or technology, builds credibility far faster than working the room as "someone who buys businesses". Once you own your first business, you can often join as a member, which makes you a peer rather than an outsider.
2.5 Inbound and succession marketplaces
- Once a platform has a reputation, owners and advisers start approaching it directly. Over time, inbound interest can become one of the most efficient sourcing channels and a sign that the platform's reputation is working in its favour.
- Online business-transfer marketplaces exist, some publicly backed, such as Germany's nexxt-change. They mostly list smaller businesses and quality is mixed, but they occasionally surface good targets.
Summary of sourcing channels:
| Channel | Main advantage | Trade-off |
|---|---|---|
| Brokers | Transaction-ready sellers, faster process | Competition, potentially higher prices |
| Direct outreach | Early access, greater control | Low conversion, long lead times |
| Intermediaries | Trusted introductions | Requires sustained relationship-building |
| Sector networks and previous sellers | Credibility and warm referrals | Takes time to establish |
| Inbound and marketplaces | Additional deal flow with limited direct outreach | Variable quality and volume |
First meetings are about trust, not price. The owner is deciding whether you are someone they would hand their life's work to.
What owners often want to know early:
- What happens to their staff, many of whom they have known for decades.
- What happens to their clients, and to the company's name.
- What their own role will be, and for how long.
- Whether they will be treated fairly.
Practical points:
- Selling is emotional. The business is often the owner's identity. Expect second thoughts, sometimes very late. Seller's remorse is one of the most common reasons deals die after an LOI.
- Spouses and family are often invisible but decisive. A spouse who dislikes the deal can kill it.
- Sellers could anchor on hearsay, such as "my friend sold for 8x" or a revenue multiple from a bigger deal. Good acquirers explain early how valuation works, so expectations are realistic before months are spent.
- The owner's advisers shape expectations. Their accountant or tax adviser needs winning over too.
- Be honest about what will change. An acquirer who promises nothing will change, then changes everything, loses the next seller's trust.
- Speak the owner's language, literally. Local-language outreach and meetings materially improve response and trust.
Field lesson: In early conversations, find out why the seller is really selling. Their underlying motivation shapes how you frame the discussion, what flexibility you have on structure, and how you build your offer. Ask open questions like:
- "What do the next five years look like for you and the business?"
- "What do you enjoy most about running the company? What has become harder?"
- "Have you thought about what you would like to do if you weren't running the business every day?"
Sellers tend to fall into recognisable archetypes, for example:
- Ready to step away: they want to stop working and go sailing or travelling, and often have a clear number and date in mind. Certainty and timing matter most.
- Securing a legacy: they’re retiring but want their employees and customers looked after. They’re usually less sensitive on price and timing, and more open to deferred consideration and earn-outs.
- Moving on to the next thing: they’re cashing out to fund a new venture, so they will push to maximise cash at completion.
Knowing which one you’re dealing with tells you where you can be flexible and where you can’t.
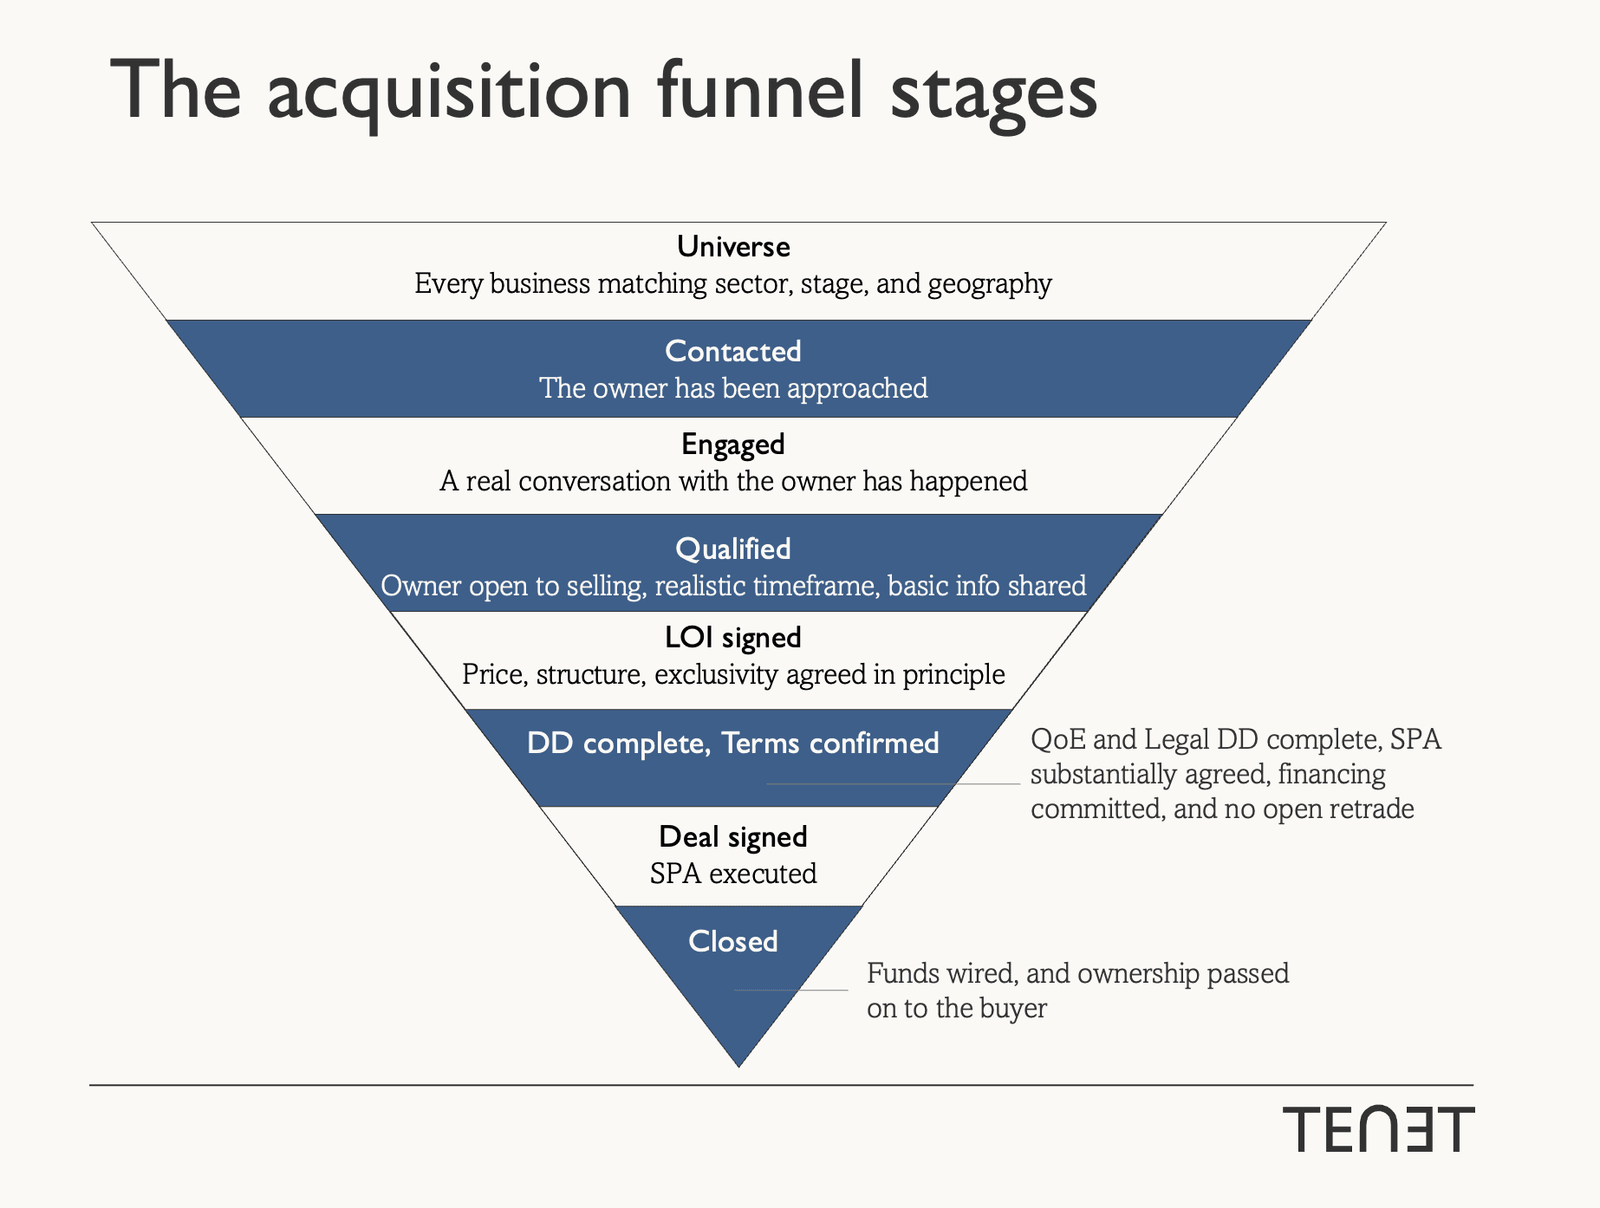
Sourcing is a funnel, and good acquirers manage both its volume and its conversion.
Deal timelines are uncertain, and transactions can fall apart at any stage. However confident you feel about the deal under LOI, never assume it will close and keep the pipeline full at the pre-LOI stages.
Equally, be fair to sellers and don’t sign LOIs loosely: treat them as a commitment made with every intention of closing, not as an option.
At the same time, kill weak deals early. Every opportunity pursued consumes founder time and adviser fees, and the cheapest diligence is an early "no".
 (opens the image full size in a new tab)
Approximate rules of thumb:
- Direct outreach turns only a small share of contacts, typically low single-digit percent, into real conversations. Only a fraction of those close.
- Proprietary deals often take 6–24 months from first contact to completion.
- Brokered deals typically run 4–9 months from teaser to completion.
Early screening criteria that kill most deals:
- Profit history: stable over three or more years, not a one-year spike.
- Revenue quality: recurring or contracted revenue rather than one-off projects.
- Owner dependence: is there a second layer of staff who manage clients and delivery without the owner?
- Customer concentration: a single client above roughly 20% of revenue is a common flag, and can be a deal-killer unless the risk is priced in, typically through an earn-out tied to retaining that client (more on this in later chapters).
- Fit with the platform: sector, geography and services.
- Seller motivation and timing: real, and within a realistic window.
- Price expectations: within range after an early valuation conversation.
Red flags at the sourcing stage:
- Adjusted EBITDA far above the profit shown in filed accounts and a low cash conversion percentage.
- A sharp jump in profit just before the sale.
- Increasing EBITDA ahead of the exit but no additional cash conversion.
- An owner who insists on all cash and an immediate exit, with no handover at all.
- An owner who won't introduce key staff or a second-in-command at any stage.
- A retirement story alongside declining revenue or lost key clients.
- A business listed for a long time, or relisted with a new broker.
- A broker running a full auction on a very small business.
- Key clients or staff related to the owner.
- A seller using your offer to negotiate with another buyer.
Track this: review funnel numbers every quarter: conversion between stages, time from first contact to completion, median EV/EBITDA across the funnel, and why deals were lost. Zooming out to view the funnel in aggregate often reveals a lot about pipeline quality and flags any early interventions needed.
Even a well-sourced deal can turn competitive (although, there are fewer buyers in your target size range). Owners test your price, hire an adviser or take a call from another buyer. When that happens, it helps to know who you’re up against.
- Other roll-ups and buy-and-build platforms in the same sector, some could be pursuing the same targets for the same reasons.
- PE-backed platforms buying add-ons. They can justify higher prices because they price in synergies.
- Other financial buyers, such as search funds, independent sponsors and serial acquirers. Search funds are growing across Europe, and compounders are particularly active in the Nordics.
- Trade buyers, usually local competitors. They are often the most dangerous bidder because they already know the clients.
- Management buyouts and family successors. Rarely the highest bidder, but sellers often favour them for continuity.
The good news is that at this size, the highest bidder doesn't always win. Owners and brokers fear deals that collapse late, and owners care about what happens after the sale. Keep them in mind during sourcing conversations, and ensure your messaging reflects this.
What wins deals:
- High certainty of closing: funding in place, a clear process, a known timeline.
- Speed: fast responses and a quick indicative offer.
- Reputation and references: letting the owner speak to people who sold to you before.
- Fit: a credible plan for the owner's staff, clients and brand, and a realistic role for the owner.
- Flexible structure: matching the seller's personal and tax goals. For example, more cash at completion for a lower headline price, or rollover equity for an owner who wants upside.
- A credible number. Sellers and brokers discount offers from buyers known to cut the price after diligence. An honest offer, with the EBITDA it's based on stated up front, often beats a higher one the seller suspects will shrink. It also means that if diligence does find problems, the price moves by agreed arithmetic rather than as a retrade (more on this in Chapter 2).
When losing is the right outcome: when a trade buyer with obvious synergies wants the business badly, or a PE-backed platform pays up for an add-on. Walking away is part of the job.
Sourcing is a fixed cost that truly pays off at volume. The team, data, outreach tools and broker relationships cost roughly the same whether you close two deals a year or ten.
- Dead-deal costs are large relative to deal size. Legal and diligence fees on deals that fail can be significant at €0.5–2m EBITDA, which is why discipline early in the process matters.
- Pressure to deploy capital pushes acquirers into worse deals. Be honest with yourself about whether pipeline quality is keeping pace with the deployment targets you've set.
- Each closed deal lowers the cost of the next. Referrals, reputation and standard documents compound.